Reviews
Boston Dynamics Executive Deal Memo: Valuation, Business Model, and Industrial Robotics IPO Outlook
Valuation Date: March 2026
Sector: Industrial Quadrupedal & Humanoid Robotics, Autonomous Truck Unloading, Industrial Embodied AI.
Target Asset: Boston Dynamics Inc. (USA, Waltham, Massachusetts).
Ownership: Hyundai Motor Group (80%), SoftBank Group (20%).
Executive Snapshot & Valuation Triangulation
| KEY TAKEAWAY |
| Boston Dynamics is the world’s most iconic robotics enterprise, successfully pivoting from legendary YouTube viral demonstration videos into commercial enterprise revenue generators. Acquired by Hyundai Motor Group in 2021 at an enterprise valuation of $1.1 billion, the company commercialized two revenue engines — Spot (industrial inspection quadruped with over 1,500 units deployed) and Stretch (autonomous mobile container unloading robot operating with DHL and Maersk). With the historic retirement of its legacy hydraulic Atlas in favor of an ultra-athletic, fully electric New Atlas for automotive manufacturing, Boston Dynamics is primed for an eventual spin-off IPO valued between $3.5 billion and $5.5 billion. |
1.1. Commercial Product Lines and Hardware Evolution
- Spot (The Industrial Quadruped): Deployed in oil refineries, nuclear facilities, mining shafts, and construction sites to automate routine thermal, acoustic, and radiation inspections with certified IP67 ingress protection.
- Stretch (Autonomous Logistics Unloader): Designed specifically to solve one of the most grueling warehouse jobs — manually unloading shipping containers and trailers. Stretch unloads up to 800 heavy cardboard boxes per hour autonomously.
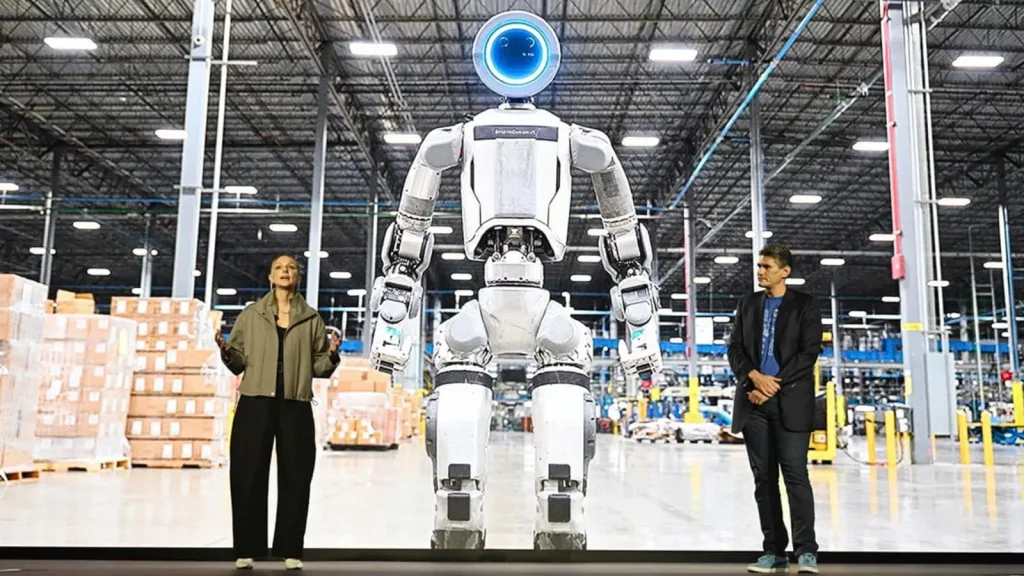
- New Electric Atlas: A radically redesigned humanoid robot powered by custom high-output electric rotary actuators delivering 360-degree joint range of motion, purpose-built for Hyundai assembly lines.
1.2. Valuation Triangulation Scenarios
| Valuation Scenario |
Target Enterprise Value |
Valuation Methodology |
Operational Rationale |
| Hyundai Acquisition Floor |
$1.1 – $1.5 Billion |
Historical M&A Cost Basis |
Underpinned by physical IP, patents, and core Spot fleet recurring maintenance revenue |
| Base Case (Spin-Off IPO Target) |
$3.5 – $4.5 Billion |
14× – 16× Forward Revenue |
Stretch multi-year enterprise contracts with DHL/Maersk ($200M+ backlog); early Atlas deployments |
| Bull Case (Embodied AI Re-Rating) |
$6.0+ Billion |
Premium Robotics Multiple |
Universal factory deployment across Hyundai/Kia automotive manufacturing networks globally |
Triangulated Comparable Transactions (Comps)
| Player |
Valuation / Cap |
Strategic Benchmark for Boston Dynamics |
| Symbotic (SYM) |
~$18 Billion |
Shows massive market valuation premium for industrial-grade box and pallet automation |
| Figure AI |
$2.6B – $10B+ |
Figure claims AI supremacy; Boston Dynamics answers with 30 years of unrivaled mechatronic durability |
| KUKA / Fanuc / ABB |
Industrial P/E Benchmarks |
Traditional stationary arm robotics trade at 15–20× earnings; Boston Dynamics commands higher mobile automation growth multiples |
Risk Audit & Due Diligence Checkpoints
- Past R&D Heavy Heritage: Historically spent decades as an academic DARPA contractor; transforming engineering culture into cost-disciplined serial manufacturing requires ongoing vigilance.
- High Unit Cost of Spot and Stretch: With Spot priced at ~$75,000+ and Stretch over $300,000, lower-cost Asian competitors (Unitree) are exerting price pressure in non-critical sectors.
- Hyundai Captive Dependency: Balancing internal Hyundai plant commitments against open commercial sales to rival automotive OEMs (Ford, BMW, GM).