Photo: Audy of Course / Pexels
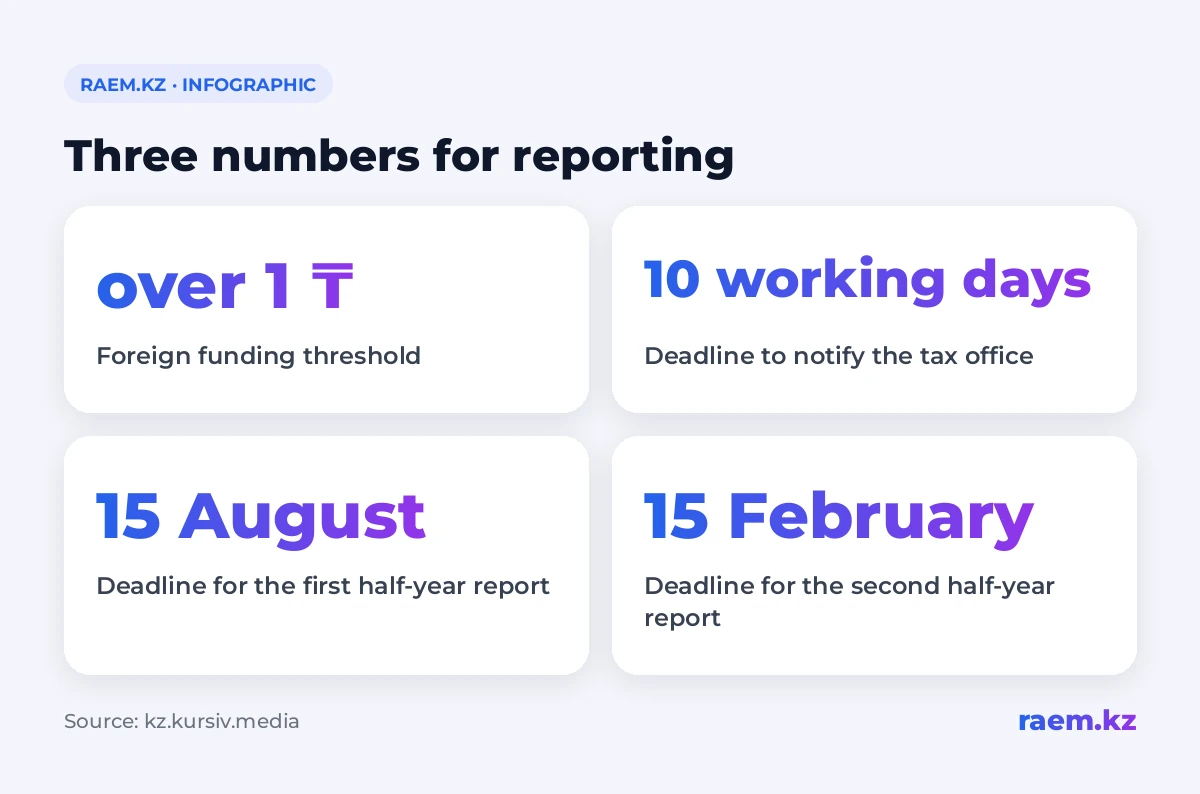
In Kazakhstan, foreign funding over 1 tenge must be reported to the tax authorities if it pays for certain activities. A transfer from a relative abroad does not, by itself, create this obligation. Order No. 763 of 9 November 2026 updates the reporting rules, including forms and document processing (kz.kursiv.media). The threshold of more than 1 tenge was already in place.
Who must report money from abroad
The requirement applies to individuals, legal entities and organisations’ structural units. What matters is which activity receives the foreign funding:
- Legal assistance, including advice and legal information, as well as defending and representing the interests of individuals and organisations.
- Public opinion research and sociological surveys, including publication of the results. Commercial research is excluded.
- Collecting information for non-commercial purposes, along with analysing and sharing it.
Civic organisations and research centres may fall under these rules. The obligation depends on which activity receives the funding.
Which funds and property must be reported
The rules cover money and other property received from foreign states. Funding sources also include international and foreign organisations, foreign nationals and stateless people.
One detail matters here: the threshold is “more than 1 tenge”. Saying that even exactly 1 tenge must be reported is inaccurate.
Other tax oversight issues are covered in the articles on monitoring mobile transfers and data on purchases by Kazakhstan residents.
When to notify the tax authorities
You have 10 working days to submit a notification. The clock starts on the day after you receive the money or property.
The notification and the half-year report are two separate obligations. After notifying the authorities of a receipt, you must also report the funding received and spent during the half-year.
When to submit half-year reports
Reports must be submitted using form 018.00ф. The deadline is the 15th day of the second month after the reporting half-year ends.
| Period | Filing deadline |
|---|---|
| First half of the year | By 15 August |
| Second half of the year | By 15 February of the following year |
The form lists the amounts received and spent. It must also include property and funding sources. Foreign currency receipts are converted into tenge at the market exchange rate on the relevant date.
What information will appear in the register
The State Revenue Committee compiles a database of foreign funding recipients. The public register lists the recipient’s full name or the organisation’s name. For a legal entity, it includes the business identification number (BIN), if it has one.
The register also includes the name of the foreign funding source and the amount of money actually received or the value of the property in tenge.
The register is updated after each half-year. Under the updated rules, information must be published by the 20th day of the month following the deadline for submitting half-year reports.
Put simply
A transfer from a relative abroad does not automatically require this special reporting. The obligation applies to foreign funding of more than 1 tenge for the activities listed above.
If you receive this kind of funding, check what it is for and the date you received it. For the notification deadline, count 10 working days from the following day. Separately, note the deadline for the half-year report: 15 August or 15 February of the following year.