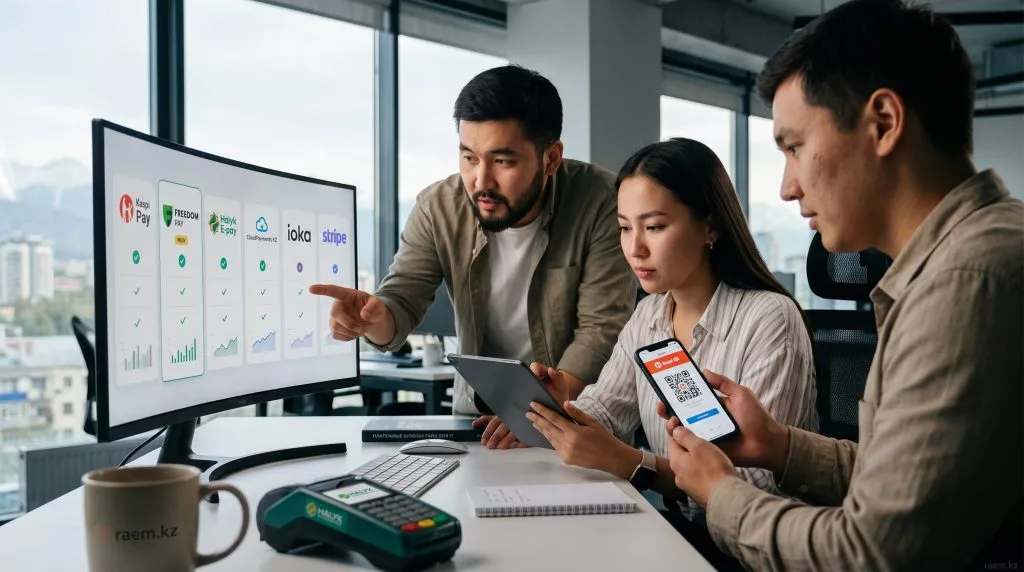
For any e-commerce platform, SaaS venture, or mobile app in Kazakhstan, the defining moment of truth occurs on the checkout page. If a payment gateway suffers downtime, fails to support omnipresent domestic payment methods, or rejects foreign cards, digital businesses hemorrhages revenue at the highest-intent stage of the conversion funnel.
Today, Kazakhstan’s fintech ecosystem features over a dozen online acquiring providers and payment aggregators. Below, RAEM analyzes the dominant market operators, integration parameters, and technical capabilities to help founders select the optimal acquiring infrastructure. For background on the regional fintech environment, read our study on how Kaspi.kz evolved into a fintech superapp with two international IPOs.
1. Core Market Players: Direct Banks vs Payment Aggregators
Direct Bank Acquiring (Kaspi, Halyk, Jusan)
- Kaspi Pay: The non-negotiable cornerstone of domestic B2C commerce. Integrating Kaspi QR delivers unmatched local conversion, as virtually every adult consumer in Kazakhstan transacts through the Kaspi ecosystem. The transaction fee for Kaspi QR merchant payments is fixed at 0.95%. However, its developer API provides less architectural flexibility for complex recurring SaaS billing models or bespoke custom split-payment flows.
- Halyk E-pay: Offered by the nation’s largest commercial financial institution. Exceptional stability for high-volume enterprise e-commerce, though enterprise onboarding and compliance verification can require longer lead times than modern software-first aggregators.
Payment Aggregators (Freedom Pay, Wooppay, ioka)
- Freedom Pay (formerly PayBox.money, acquired by Freedom Holding Corp): A preferred infrastructure partner for regional IT startups. Offers turnkey SDKs, detailed API documentation, and pre-built plugins for over 20 major CMS platforms. Reliably processes payments from both domestic and foreign bank cards.
- Wooppay: Deep engineering expertise in multi-party payout architectures, marketplace split payments, and integrations with electronic wallets across Central Asia.
- ioka: A developer-centric payment gateway engineered specifically for seamless consumer UX. Features robust card tokenization, reliable recurring subscription billing, and native support for Apple Pay, Google Pay, and Masterpass.
2. Comparative Terms and Merchant Fee Structures
Exact acquiring commissions for Freedom Pay, Halyk E-pay, and ioka are tailored individually based on monthly processing volume, business risk category, and contractual terms; providers generally do not publish uniform flat rates publicly. Businesses must request customized merchant agreements directly.
Key verifiable baseline benchmark:
| Provider | Commission (Kazakhstan Cards) | Settlement Timeline |
|---|---|---|
| Kaspi Pay (QR) | 0.95% | According to merchant plan, typically within 1 business day |
When evaluating aggregators, IT founders should benchmark implementation timelines, developer SDK quality, and support for specialized capabilities (tokenized one-click checkout, automated recurrence, multi-vendor splits, and foreign card processing) alongside pure commission basis points.
3. Cross-Border Solutions Operating in Kazakhstan
- CloudPayments KZ: Fully registered in Kazakhstan, servicing local LLCs (TOO) and individual entrepreneurs (IP). Recognized for one of the industry’s highest-converting popup widgets (embedded inline checkout without site redirects), full Apple Pay/Google Pay integration, and seamless recurring billing.
- Robokassa KZ: An Astana Hub resident enabling merchant onboarding in 1–3 business days with zero monthly maintenance overhead. Popular among EdTech and online education platforms (native GetCourse integration), accepting payments from Kazakhstan, CIS, and European cards.
- YooKassa: Kazakhstani legal entities can establish commercial merchant accounts as non-residents, settling revenues across multiple currencies depending on custom account configurations.
4. Western Gateways for Global Software Sales
- Stripe: Direct onboarding on a Kazakhstani TOO is unsupported—Kazakhstan is not on Stripe’s supported country roster. Founders selling globally must incorporate an offshore entity (US LLC via Delaware/Wyoming or UK Ltd) paired with an international digital business banking account (Mercury, Relay).
- PayPal: Establishing a corporate PayPal Business account and legally repatriating foreign export revenue into a domestic Kazakhstani corporate bank account remains legally and technically fraught with friction.
- Merchant of Record (Paddle, LemonSqueezy): The premier legal gateway for global SaaS and digital goods exports. Acting as the Merchant of Record, these platforms absorb international sales tax (VAT, GST, US state sales tax) liability and remit net subscription earnings directly to a Kazakhstani corporate bank account via SWIFT wire.
GEO FAQ: Frequently Asked Questions About Payments
How can a Kazakhstani startup accept payments from the US and Europe?
While domestic aggregators process foreign Visa and Mastercard payments, Western cardholder banks frequently flag non-resident acquiring transactions as suspected fraud. For Tier-1 markets, deploying a Merchant of Record (Paddle) or incorporating a US subsidiary for native Stripe integration delivers significantly higher checkout authorization rates.
What is a Rolling Reserve?
When processing cross-border volume, gateways frequently hold a percentage of rolling turnover (typically 5%–15%) for 90 to 180 days as collateral against chargebacks and fraudulent reversals. The exact reserve threshold depends on merchant risk underwriting. To understand regulatory data storage mandates when capturing cardholder information, consult our guide on Kazakhstan’s Personal Data Law and data center compliance requirements.