Photo: Kampus Production / Pexels
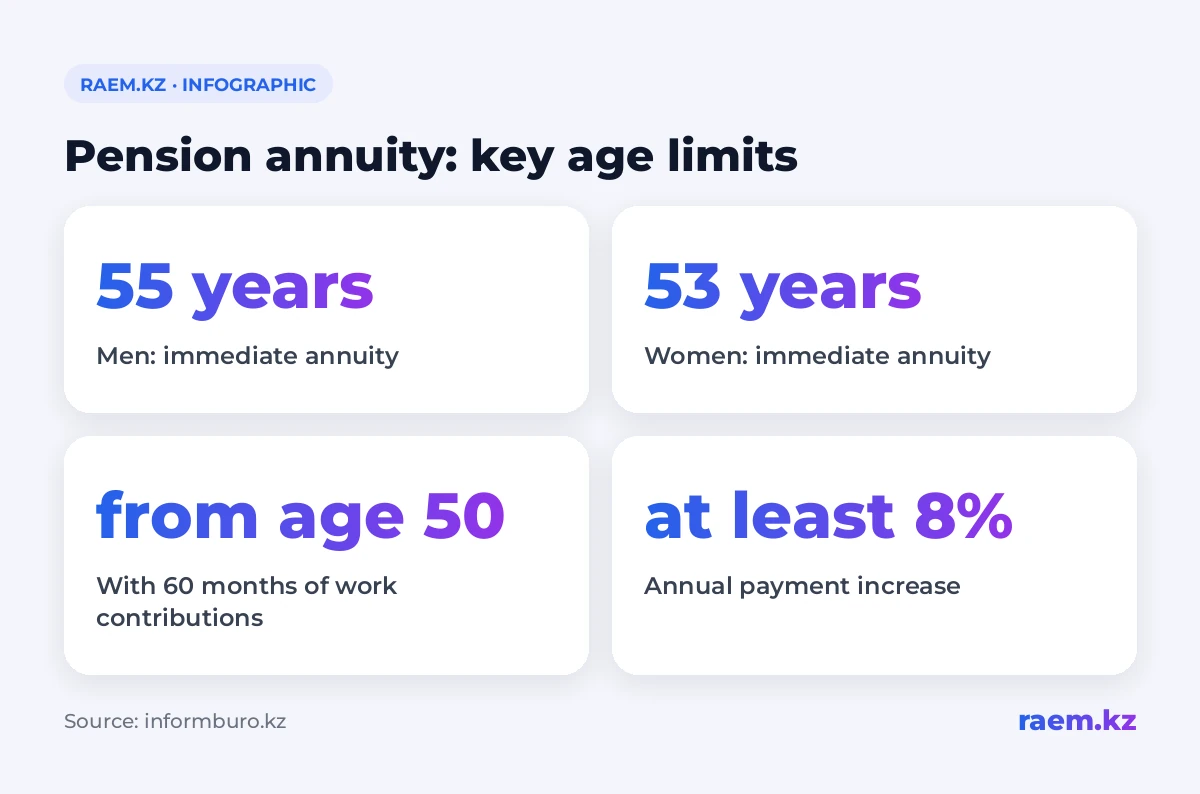
In Kazakhstan in 2026, men can start receiving pension annuity payments at 55 and women at 53, provided they have enough pension savings. Those with at least 60 months of mandatory occupational pension contributions can start receiving payments at 50, provided they have sufficient savings. The insurance company makes regular payments for life. The Committee for Regulation and Oversight of Social Protection at Kazakhstan’s Ministry of Labour and Social Protection explained the terms (informburo.kz).
How a pension annuity works
You transfer your pension savings to an insurance company. In return, it commits to making regular payments for the rest of your life. Payments continue even if the total paid out exceeds the amount transferred.
Pension annuity payments in Kazakhstan totalled 81.5 billion tenge in the first eight months of 2026. Insurance premiums reached 624.7 billion tenge.
When you can sign a contract
The minimum age depends on the type of annuity and whether mandatory occupational pension contributions have been made. To start receiving payments earlier, you need at least 60 months of these contributions — five years.
| Option | Age |
|---|---|
| Immediate annuity for men | From 55 |
| Immediate annuity for women | From 53 |
| Start of payments with 60 months of mandatory occupational contributions | From 50 |
| Signing a deferred annuity contract | From 45 |
| Signing a deferred annuity contract with 60 months of mandatory occupational contributions | From 40 |
With a deferred annuity, the terms of future payments are agreed in advance, but payments begin later. The age at which you can sign the contract differs from the age at which payments start. You also need sufficient savings to sign a contract.
How much you need in savings and how payments grow
The amount required is calculated individually. It depends on your age and the terms of your future payments. Reaching the required age alone therefore does not mean you can sign a contract.
Payments increase by at least 8% each year. The exact indexation terms are set out in the contract. You can compare future payments from the Unified Accumulative Pension Fund (UAPF) with those from an insurer using the pension calculator on the fund’s website.
A separate article explains how Kazakhstan plans to increase future pension payments.
Who receives the money after the recipient dies
The contract may include a guaranteed payment period. If the recipient dies before it ends, their heirs receive the money. When choosing an offer, check whether it includes such a period and how long it lasts.
This is a provision in the contract with the insurer. It is separate from the inheritance of any remaining pension savings in the UAPF.
Can you keep working?
Receiving annuity payments does not prevent you from working. However, the contract does not give you early access to a state pension: eligibility is determined under the general rules.
What to compare before signing
Before signing a contract, compare insurance companies’ offers on four points:
- the size of the first payment;
- how annual increases work;
- the terms of the guaranteed period;
- whether the contract can be amended.
One provider is the State Annuity Company, which operates under the Ministry of Labour. It provides annuity insurance services and advice on calculating whether your savings are sufficient.
In simple terms
An annuity lets you exchange your pension savings for regular payments for life. First, check the age requirements and request an individual calculation. Then compare insurers’ offers with the UAPF calculation, paying attention to the first payment, indexation and the guaranteed period.