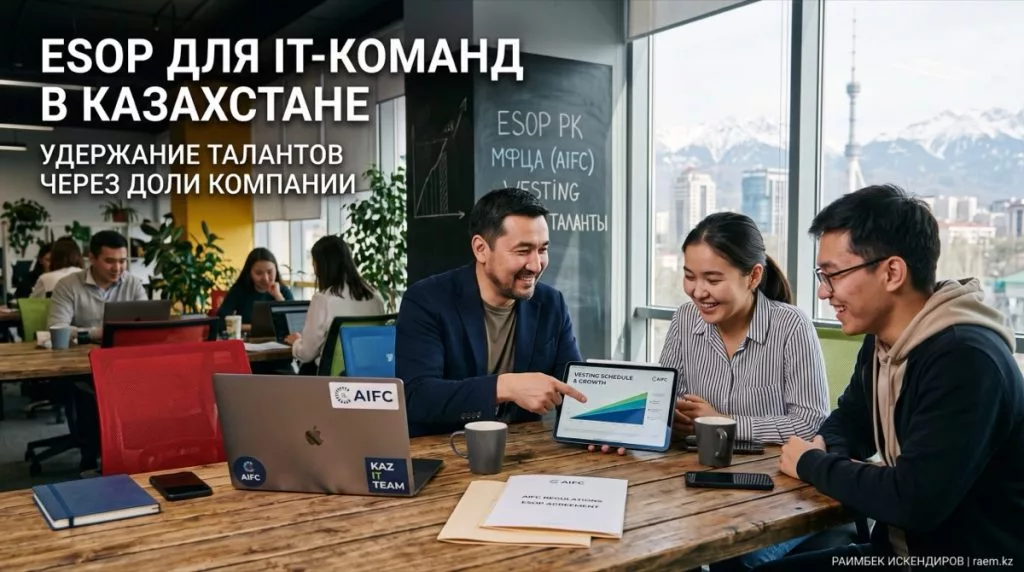
In the fiercely competitive technology industry, retaining senior software architects, engineering leads, and C-level executives with cash salaries alone is often financially unfeasible for early-stage startups. Global tech hubs rely on Employee Stock Option Plans (ESOP) to align staff interests with enterprise valuation. In Kazakhstan, implementing ESOP historically encountered severe statutory hurdles under classical corporate law. Today, the Astana International Financial Centre (AIFC) provides a robust legal framework rooted in English common law. RAEM.KZ analyzed the legal architecture, vesting mechanics, and tax considerations.
1. The Problem with Classical Kazakhstan LLPs (ТОО) for Options
The standard corporate vehicle in Kazakhstan is the Limited Liability Partnership (LLP / ТОО). Governed by the Civil Code and the Law on LLPs, standard partnerships are poorly suited for dynamic option pools:
- Notarial and State Re-registration: Every minute equity transfer requires notarial execution, corporate amendments, and re-registration with state authorities.
- Statutory Preemptive Rights: Existing participants possess rigid statutory priority rights to acquire departing shares, complicating conditional employee grants.
- Absence of Non-Voting Share Classes: In an LLP, every partner gains statutory governance rights, inspects confidential ledgers, and can paralyze shareholder votes.
2. The Solution: AIFC Jurisdiction and English Common Law
The Astana International Financial Centre (AIFC) operates under an independent legal regime based on principles of English common law, recognized by Kazakhstan’s Constitution. Incorporating a holding or operating entity as a private company within the AIFC unlocks standard venture tools:
- Flexible share capital structures with separate non-voting share classes (Class B shares);
- Statutory recognition of convertible instruments (SAFE, KISS, Convertible Notes);
- Standard option agreements with enforceable conditional vesting schedules;
- Dispute adjudication via the independent AIFC Court and International Arbitration Centre (IAC).
Comparison: Traditional LLP vs. AIFC Entity for Option Plans
| Parameter | Traditional LLP (ТОО) | AIFC Private Company |
|---|---|---|
| Applicable Law | Kazakhstan national legislation | AIFC legal framework & English common law |
| Equity Transfer Process | Mandatory notary visit & state re-registration | Internal company register update |
| Non-Voting Shares | Not provided by statute | Fully permitted (Class B Non-Voting) |
| Vesting & Cliff Enforcement | High judicial risk in local civil courts | Fully enforceable under AIFC Court precedents |
| Option Pool Setup | Complex workarounds or phantom agreements | Standardized 10–15% reserved unallocated pool |
3. Option Mechanics: Understanding Cliff and Vesting
An option is not an outright gift; it is a legal right to purchase shares at a predetermined exercise price (strike price) upon meeting defined service tenure or milestone metrics.
Vesting Schedule: The timeline over which an employee earns the right to exercise their options. The global venture standard is a 4-year vesting schedule, distributing 25% of the total allocation each year.
The Cliff Period: Typically set at 1 year. If a team member leaves before completing 12 months of service, they forfeit 100% of their options. Upon passing the one-year mark, the initial 25% tranche vests immediately, after which remaining shares vest monthly or quarterly.
4. Alternative Route: Phantom Shares
For startups operating strictly as classical LLPs that cannot yet justify AIFC corporate restructuring, Phantom Shares offer a pragmatic synthetic alternative. Rather than granting actual corporate equity, the founder executes a civil contract mirroring corporate value growth: promising a cash bonus pegged to future valuation gains or liquidity exit proceeds.
5. Required Legal Documentation Package
- ESOP Plan Rules & Option Agreements: Outlining strike prices, vesting timetables, cliff periods, and good/bad leaver clauses;
- Articles of Association Amendments: Formalizing option share pools and non-voting equity classes in the corporate charter;
- Intellectual Property (IP) Assignment Agreements: Guaranteeing that all software code, algorithmic architectures, and designs created by option recipients belong irrevocably to the company;
- Non-Disclosure (NDA) and Non-Compete Undertakings: Protecting proprietary trade secrets upon employee departure.
Structuring equity compensation early ensures sustainable founder capitalization, protects minority rights, and positions Kazakhstani startups for institutional Series A investment.