Operating framework for Guarantee Fund 1, updated as of September 2026.
Insufficient physical collateral is one of the most pervasive hurdles preventing viable enterprise projects from securing commercial bank debt. The Damu Entrepreneurship Development Fund’s Guarantee Fund directly mitigates this financing bottleneck: by assuming a substantial portion of the default risk, the state fund enables businesses to unlock bank loans, industrial equipment leasing, and structured credit lines.
Crucial Clarification: A loan guarantee is neither a grant nor a non-repayable cash subsidy. The guarantee does not reduce the borrower’s underlying debt liability and does not constitute automatic loan approval. Credit committees at commercial partner banks and leasing institutions independently evaluate business solvency and project risk prior to issuing funds.
Core Program Parameters and Financing Limits
Under statutory Guarantee Fund 1 guidelines, eligible commercial financing can reach up to 7 billion tenge per enterprise. Damu can provide a credit guarantee covering up to 85% of the total loan principal, subject to an absolute guarantee ceiling of 3.5 billion tenge.
- Maximum Project Financing: Up to 7 billion KZT;
- Maximum Guarantee Coverage: Up to 85% of financing, capped at 3.5 billion KZT;
- Eligible Purposes: Capital asset investments, working capital replenishment, and debt refinancing;
- Permitted Currencies: Kazakhstani tenge (KZT) and/or approved foreign currencies;
- Guarantee Duration: Operates for the loan term plus up to five additional calendar months post-maturity.
These figures represent structural program limits rather than an entitlement to maximum allocations. Actual approved loan amounts and guarantee ratios depend on debt service coverage ratios (DSCR), collateral liquidity, and partner bank underwriting.
The guarantee absorbs lender default risk, but does not absolve the entrepreneur from complete debt repayment obligations.
Eligibility Criteria and Prioritized Economic Sectors
Eligible applicants include private commercial enterprises and legal entities registered within the Astana International Financial Centre (AIFC). The program spans a broad catalogue of priority economic sectors, verified by official OKED industry codes:
- Agriculture, agribusiness, livestock, and agro-industrial processing;
- Manufacturing, heavy industry, metallurgy, and machinery engineering;
- Transportation, warehousing, cross-border transit logistics, and postal operations;
- Healthcare, private clinical services, pharmaceuticals, and social infrastructure;
- Education, vocational training centers, and scientific research institutions;
- Information technology, software development, telecommunications, and digital infrastructure.
Superficial alignment with a general sector title is insufficient. Prior to formal submission, applicants must verify exact primary and secondary OKED activity codes against Damu’s statutory register and confirm program participation with their financing bank.
Careful verification of OKED codes and financial eligibility prevents loan delays at commercial partner banks.
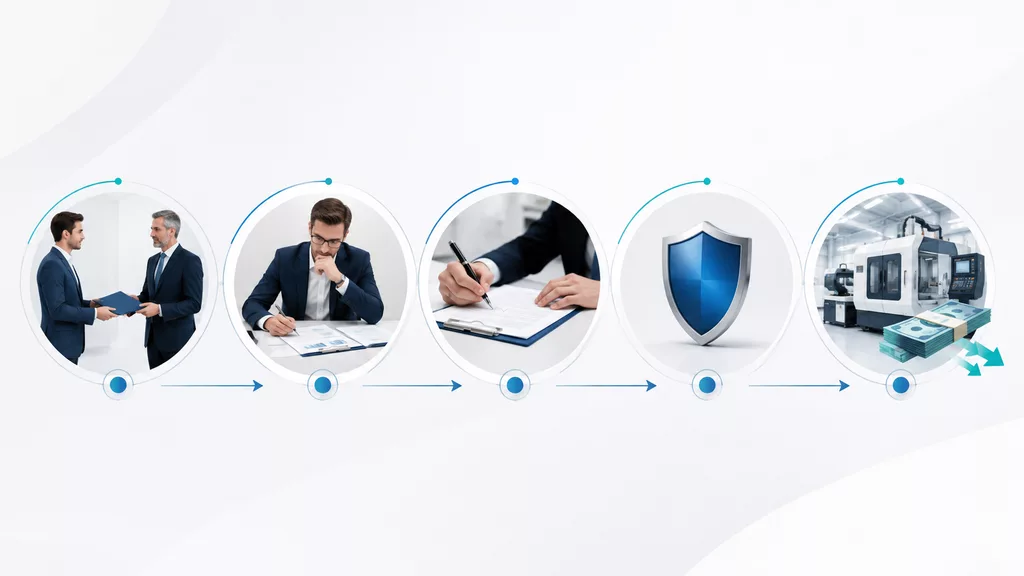
The financing journey begins with the commercial lender: application intake, risk underwriting, loan agreement, guarantee ratification, and capital disbursement.
Five-Stage Application Roadmap
- Step 1: Lender Application. The borrower submits a credit proposal and complete financial dossier to an accredited commercial bank or leasing company.
- Step 2: Underwriting and Collateral Assessment. The bank conducts credit scoring, determines the collateral shortfall, and makes an in-principle decision to seek Damu guarantee support.
- Step 3: Damu Guarantee Review. The lender forwards the project package to Damu Fund, which audits compliance with program guidelines within established statutory turnaround windows.
- Step 4: Trilateral Agreement Execution. Upon approval, a trilateral guarantee contract is signed between the borrower, the lending bank, and Damu. Damu charges a statutory 1.5% commission fee, frequently subsidized under accompanying government programs.
- Step 5: Capital Disbursement. The lender issues loan proceeds to the borrower under agreed project milestones.
Pre-Submission Verification Checklist
- Verify project OKED alignment against current priority lists and statutory exclusions;
- Confirm whether target commercial bank is an active participating partner for the specific guarantee program;
- Ensure enterprise collateral is sufficient to secure the 15–50% portion uncovered by the guarantee;
- Incorporate the 1.5% guarantee fee and closing fees into project financial models;
- Verify that commitments regarding tax growth and job creation are realistic and auditable.
Official Resources and Contacts
Borrowers must initiate inquiries directly through participating commercial banks: Damu does not independently disburse direct loans. For preliminary guarantee calculations, visit:
Official Damu Loan Guarantee Fund Portal
Directory of Damu Regional Branch Offices
Related Articles:
- Damu Offers 85% Loan Guarantees for Agricultural Working Capital: Terms and Requirements
- «Isker Aymaq»: Small Business Loan Subsidies up to 200M KZT via Damu Fund
- Archive: Karaganda Region Awards 1M KZT Youth Business Grants
In the RAEM Grants Catalog: Damu Loan Guarantee for Collateral Shortages — program terms, qualification criteria, application procedures, and direct portal links.