Photo: Kampus Production / Pexels
Who must file Form 270 for 2026 depends on income, property and the criteria set out in the Tax Code. The general filing deadline for that year is 15 September 2027. The State Revenue Committee explains the rules under the new code, which took effect on 1 January 2026 (gov.kz). Tax residents may need to file because they have income on which they must pay tax themselves, hold assets abroad or exceed the specified thresholds.
Form 270 for 2026: Who must file under the law
The filing criteria are listed in Article 417 of the Tax Code. They include obligations under specific laws, income on which individuals must pay tax themselves, and certain categories of company executives and owners and their spouses (adilet.zan.kz).
Other criteria relate to foreign accounts and assets, major purchases, digital assets and income levels. Being an employee alone does not settle the question: you need to check the other criteria. For more on this topic, see our article on universal tax declarations in 2026.
What income requires you to file a declaration
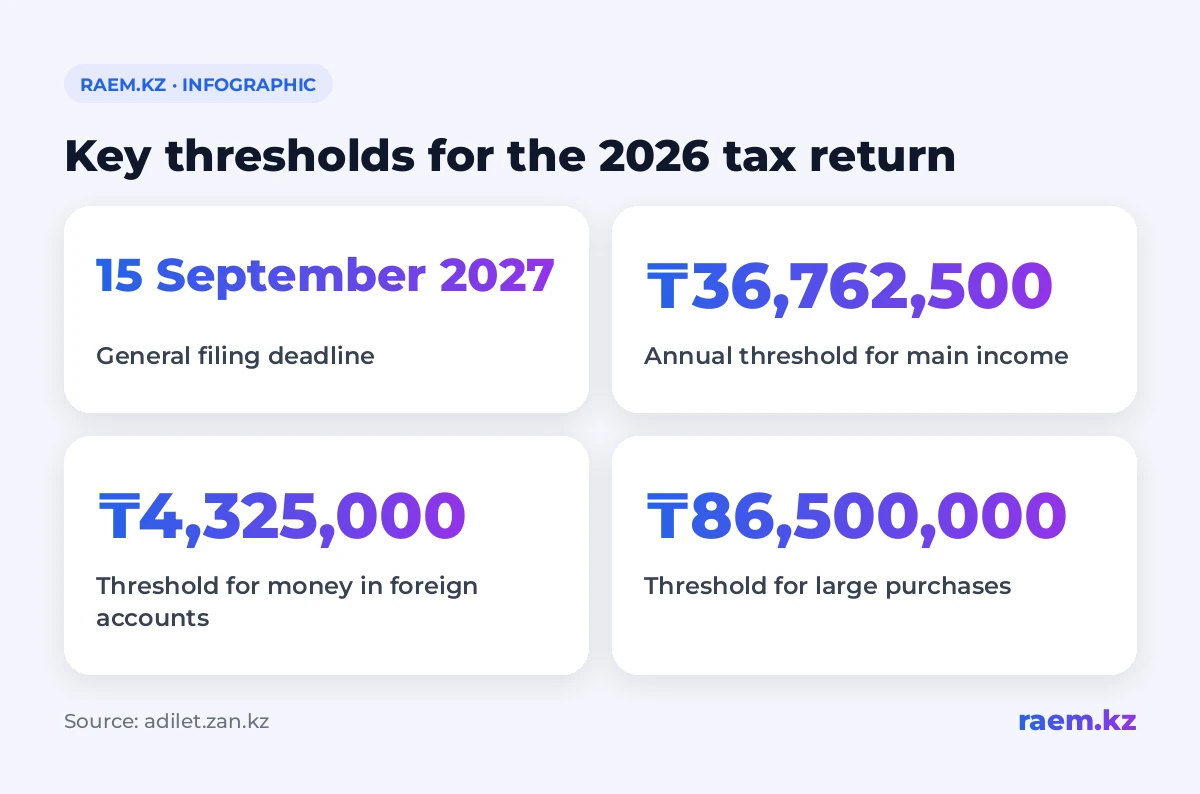
Another filing requirement applies when primary income exceeds 8,500 MCI in a calendar year. MCI stands for monthly calculation index, a figure used to calculate amounts set by law. In 2026, it is 4,325 tenge, putting the threshold at 36,762,500 tenge a year, or roughly 3.06 million tenge a month.
The tax rate on primary taxable income up to this threshold is 10%. Any amount above it is taxed at 15%. An exception to this filing requirement applies if the person’s only income is a salary already taxed at the higher rate.
Dividends have a separate threshold of 230,000 MCI, or 994,750,000 tenge for 2026. The rate is 5% up to and including that amount, and 15% on the excess. Exceeding the threshold also triggers a filing requirement. Separate rules apply to private practitioners, individual entrepreneurs and peasant farms.
Which accounts, assets and purchases to check
You may need to file even without a high income. Article 417 sets out the following criteria:
- Money in foreign bank accounts totalling more than 1,000 MCI as of 31 December — 4,325,000 tenge.
- Assets abroad listed in Article 417.
- Purchases of property specified in the code totalling more than 20,000 MCI — 86,500,000 tenge.
- Digital assets held at the end of the year.
These amounts use the 2026 MCI. The figures for that period apply when checking whether you must file for 2026, even though the declaration is submitted the following year.
When to file the declaration for 2026
Under Article 418, the general deadline is 15 September of the following year. This means the declaration for 2026 must be filed by 15 September 2027.
The declaration for 2025 had a different deadline: 15 September 2026. The State Revenue Committee’s announcement about pre-filled forms 250.00 and 270.00 referred specifically to that filing period. Individuals must check, complete or correct the automatically entered information, then confirm and submit the declaration.
What penalties apply to violations
The State Revenue Committee lists the following penalties:
| Violation | First offence | Repeat offence within a year |
|---|---|---|
| Failure to file the declaration on time | Warning | 15 MCI |
| Incomplete or inaccurate information | Warning | 3 MCI |
| Concealment of taxable items | 200% of unpaid tax | 300% of unpaid tax |
Fine amounts in tenge depend on the applicable MCI. Amounts calculated using the 2026 index cannot automatically be applied to a violation in 2027.
What to do if the tax authority sends a notice
During a desk audit, the tax authority compares tax returns with the information it holds. If it finds discrepancies, it sends a notice. You have 30 working days to comply, starting on the day after the notice is delivered.
If you agree, you need to correct your tax return and meet your tax obligations. If you disagree, submit a reasoned explanation with supporting documents. If you agree in part, you can take both steps for the relevant parts. You can check the notice and respond through the Taxpayer Account. For more details, see our article on responding to a tax notice.
Put simply: first check the filing criteria and your income and assets for 2026. Keep supporting documents and note the general deadline: 15 September 2027.