Illustration: AI
People in Kazakhstan who have transferred their pension savings to private investment managers will be able to choose a portfolio with a risk level that suits them. The conservative option will be open to everyone, while access to the others will depend on the time left until retirement. The changes are set out in Resolution No. 155 of Kazakhstan’s Agency for Regulation and Development of the Financial Market (ARDFM), dated 30 October 2026 (kursiv.media). Each manager will be able to offer up to three portfolios, but will not be required to create all three.
What will change for savers
Previously, each manager offered clients a single shared portfolio: the mix of investments holding their pension savings. Now, portfolios will be able to differ in their asset mix, risk level and the period over which returns are assessed.
The rules apply to pension savings held with private managers. Since 7 September 2026, people in Kazakhstan have been able to transfer up to 100% of their savings to these managers. The previous limit was 50%.
Who can choose each strategy
Access to a portfolio will depend on how much time a saver has left before reaching retirement age. The closer retirement gets, the less risk the rules allow.
| Strategy | Who can access it | Main investments | Return assessment period |
|---|---|---|---|
| Conservative | All savers, regardless of age | Mainly bonds | One year |
| Moderate | Savers with more than three years until retirement | Shares and bonds | Three years |
| High-risk | Savers with more than 13 years until retirement | Mainly shares | Five years |
The high-risk portfolio offers the possibility of higher returns, but the value of savings will fluctuate more sharply. Investments in foreign currencies will also be capped at 40%, 70% and 80%, respectively.
Who will cover a return shortfall
Each portfolio will have its own return benchmark. This is a composite market index that includes Kazakh and global shares and bonds. The manager’s performance will be measured against it.
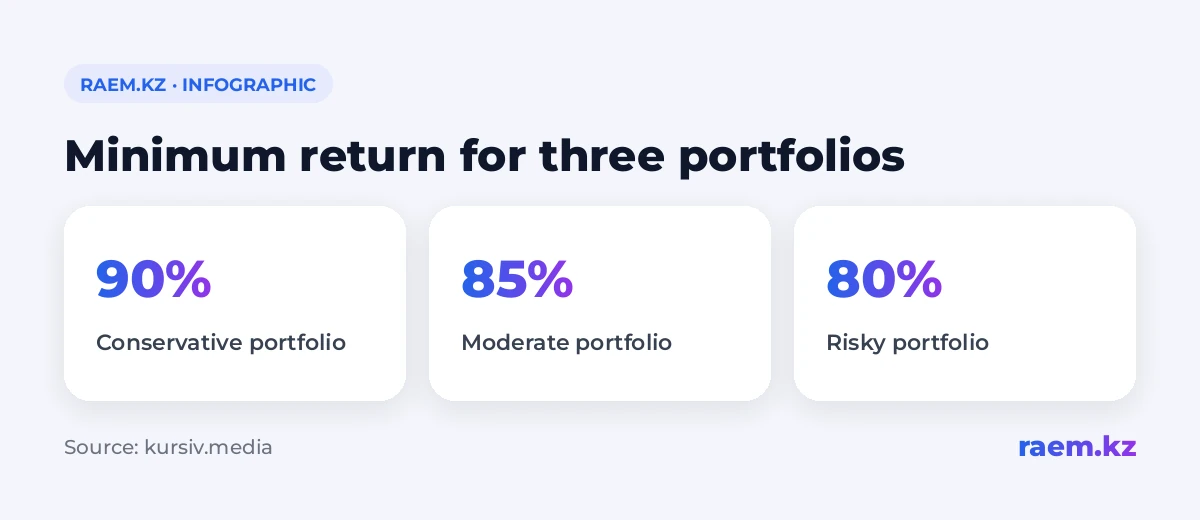
The minimum return will be tied to this benchmark: 90% of its return for the conservative portfolio, 85% for the moderate portfolio and 80% for the high-risk portfolio. There is an important detail here: these percentages represent a share of the benchmark’s return. They do not promise savers annual returns of 80–90%.
If returns fall below the minimum over the specified period, the manager will cover the difference from its own capital. Comparing returns on savings with inflation requires a separate measure: the new minimum is calculated relative to a market index.
How to split savings and switch portfolios
Savers will be able to split their savings between several managers or between portfolios offered by the same company. Switching between one manager’s portfolios will be allowed no more than once a year. Savers will need to submit an application through the Unified Accumulative Pension Fund (UAPF) website.
Each portfolio’s funds will be recorded in separate accounts at the custodian bank that holds the pension assets. The manager will be separately responsible for each portfolio’s performance.
What happens as retirement approaches
If a saver’s age no longer meets a strategy’s requirements, the UAPF will move the money into a suitable portfolio with the same manager. If no such option is available, the fund will notify the saver in advance.
After receiving the notice, the saver will be able to choose another management company or return the savings to the management of the National Bank.
When the rules take effect
The resolution will take effect 10 calendar days after its first official publication. This document specifically allows managers to create multiple portfolios.
A manager will be able to close a portfolio only after its return assessment period ends, with one year’s notice. It must also retain at least one other portfolio. If the portfolio being closed has delivered returns below the minimum, the manager will first have to compensate savers for the difference.
Put simply
Your choice will depend on the time left until retirement and the portfolios your manager offers. If you plan to transfer your savings, first check which strategies the company offers and which one you qualify for based on your age. When comparing terms, take the assessment period into account: one year, three years or five years.