Графика: raem.kz
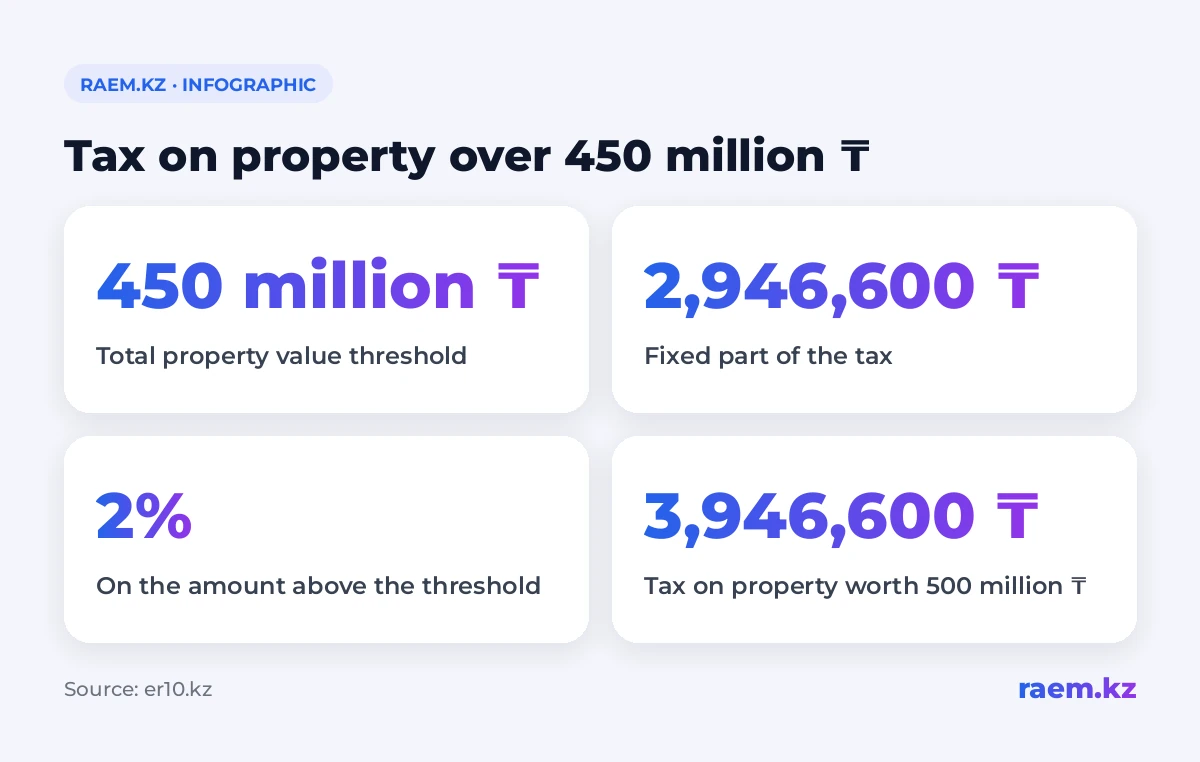
If the total value of your property exceeds 450 million tenge, the tax is 2946600 tenge plus 2% of the amount above that threshold (er10.kz). For property worth 500 million tenge, that comes to 3946600 tenge a year. The threshold applies to the combined value of properties belonging to one owner. For property held in shares, only the value of that owner’s share counts.
Which properties count towards the total
The total includes homes, buildings, summer cottages, garages, parking spaces, other buildings, structures and premises. Land plots are excluded from this calculation.
So the 450 million tenge threshold applies to an owner’s properties combined. Homes, garages and parking spaces all count. Related changes are covered in our article on taxes on expensive property.
How tax is calculated up to 450 million tenge
If the combined value of the properties is 450 million tenge or less, tax is calculated separately for each property. A total of exactly 450 million tenge still falls into this category.
Once the combined value exceeds the threshold, the total value of all the owner’s properties becomes the tax base. The calculation then uses a fixed amount plus a percentage of the value above the threshold.
How much to pay on property worth 500 million tenge
For properties with a combined value of 500 million tenge, the calculation looks like this:
| Step | Amount |
|---|---|
| Total value of properties | 500000000 tenge |
| Threshold | 450000000 tenge |
| Amount above the threshold | 50000000 tenge |
| 2% of the amount above the threshold | 1000000 tenge |
| Fixed portion of the tax | 2946600 tenge |
| Annual total | 3946600 tenge |
Here’s an important detail: the 2% applies to the amount above the threshold. In this example, it is calculated on 50 million tenge.
How ownership shares and part-year ownership are counted
If several people own shares in a property, the value counted for each person is proportional to their share. That portion forms part of the individual owner’s tax base.
If you own a property for less than a year, tax is calculated for the months you owned it. The annual amount is divided by 12 and multiplied by the number of those months.
Who pays tax on property jointly owned by spouses
For property held in joint ownership, one of the owners can pay the tax. This rule also applies to spouses.
Joint ownership should be distinguished from ownership in shares: tax on shares is calculated proportionally. For related reading, see our article on restrictions on property services (in Russian).
Put simply
If your property exceeds the 450 million tenge threshold, the calculation to use is 2946600 tenge plus 2% of the amount above the threshold. Start by listing your properties, your ownership shares and the months you owned them: these details affect the amount due.