Illustration: AI
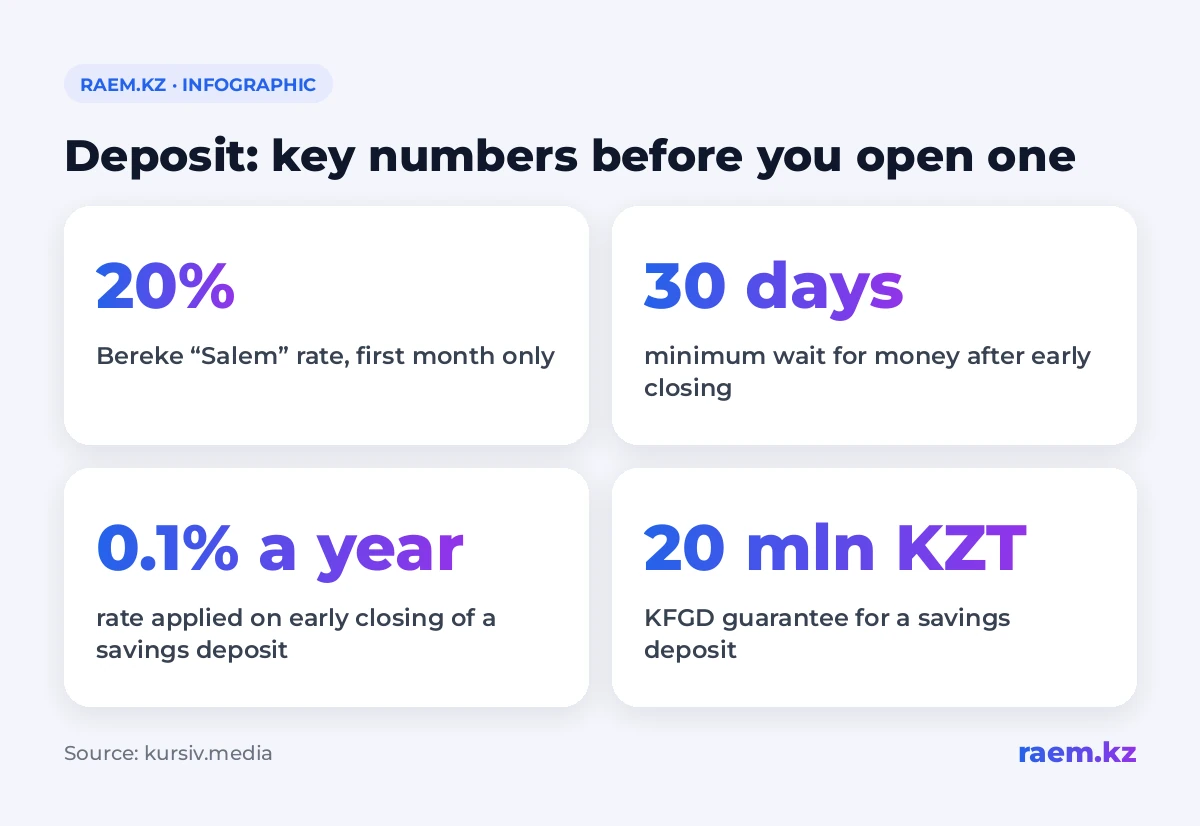
Savings deposits usually pay more interest, but if you close one early, you will wait at least 30 calendar days to get your money back. If you want free access to your savings, a demand deposit is a better fit, as long as you meet the bank’s conditions. The Kazakhstan Deposit Insurance Fund (KDIF) explains the differences; among the banks’ mass-market offers, yields of up to 20% APR (GESV) are advertised (kursiv.media).
Which deposit to choose for your money
Kazakhstan has three main types of deposits: demand, term and savings. The type determines your access to the money, what happens if you close early, and the size of the guarantee.
A demand deposit lets you top up the account and withdraw money without losing accrued interest, as long as you meet the bank’s conditions. For example, keeping a minimum balance. This option suits an emergency cushion.
A term deposit is opened for a fixed period. Early withdrawal is possible, but the bank may recalculate the interest under the contract. A savings deposit usually pays more, but partial withdrawals are not allowed.
What rates banks offer
The easiest way to compare deposit rates is by GESV, the annual effective interest rate. It accounts for capitalization: accrued interest is added to the deposit and starts earning income too.
Kursiv’s November 6 comparison lists these terms:
| Bank and deposit | Term | GESV |
|---|---|---|
| Bereke Bank, Salem | 3 months | 20% in the first month, then 19% |
| Freedom Bank, Strategy | 3 months | 19.51% |
| ForteBank, savings without top-ups | 3 months | 18.2% |
| Eurasian Bank, Turbo Deposit without top-ups | 1 month | up to 18.07% |
| Halyk Bank, QORJIN | 3 months | 18% |
| Kaspi Bank, savings deposit | 3 months | 18% |
| Alatau City Bank, Sandyq | 6 months | up to 17.81% |
Salem comes with a restriction: the offer is open to new customers and to those who have had no deposits at Bereke in the last 90 days. The minimum amount is 5 thousand tenge. At BCC, the My Goal deposit has carried a GESV of 18.04% since November 5; you can open it with as little as 1 tenge.
What a million tenge earns in three months
At a constant 20% GESV, a million tenge earns roughly 46.6 thousand tenge in three months. The actual interest payout schedule depends on the deposit’s terms.
This is a sample calculation, not a promise of income on Salem: its higher rate applies only for the first month. The exact amount depends on the nominal rate, capitalization and the number of days the money stays in the account.
Can you top up a deposit and withdraw money
The regular Kaspi Deposit offers 15% GESV and lets you top up the account and withdraw money without losing accrued interest. The 18% savings deposit can be topped up too, but you need at least 100 thousand tenge to open it.
Halyk’s QORJIN has a minimum of 50 thousand tenge. Top-ups are allowed, partial withdrawals are not. At ForteBank, a three-month savings deposit with top-ups pays 18.1% GESV: 0.1 percentage points less than the version without top-ups.
What happens to interest if you close early
If you close a savings deposit early, the interest is recalculated at 0.1% per year. You will have to wait at least 30 calendar days after applying to the bank to get your money back.
With QORJIN, no interest accrues if the money stays less than a month. After a month, early closure triggers the 0.1% annual rate. If you withdraw from the Kaspi savings deposit before the next renewal, you lose the interest for the current term.
How much KDIF guarantees
For demand and term deposits in tenge, KDIF guarantees up to 10 million tenge. For savings deposits, up to 20 million tenge. The limit covers the deposit together with accrued interest.
If you have several deposits in one bank, the guarantee applies to their total. The maximum is 20 million tenge if you hold a savings deposit in the national currency. Other types of deposits keep their own limits.
In plain words: what to check before opening
If you might need the money suddenly, pick a deposit with partial withdrawals. If you’re ready to leave the sum for a few months, compare the yield against the loss from closing early.
Before opening, check the term, the minimum amount, and the rules for withdrawal and renewal: the deposit rate may change when the term ends. For example, from November 9 Freedom Bank plans to cut the GESV on its three-month Strategy deposit to 19.20% for new and renewed deposits.