Illustration: AI
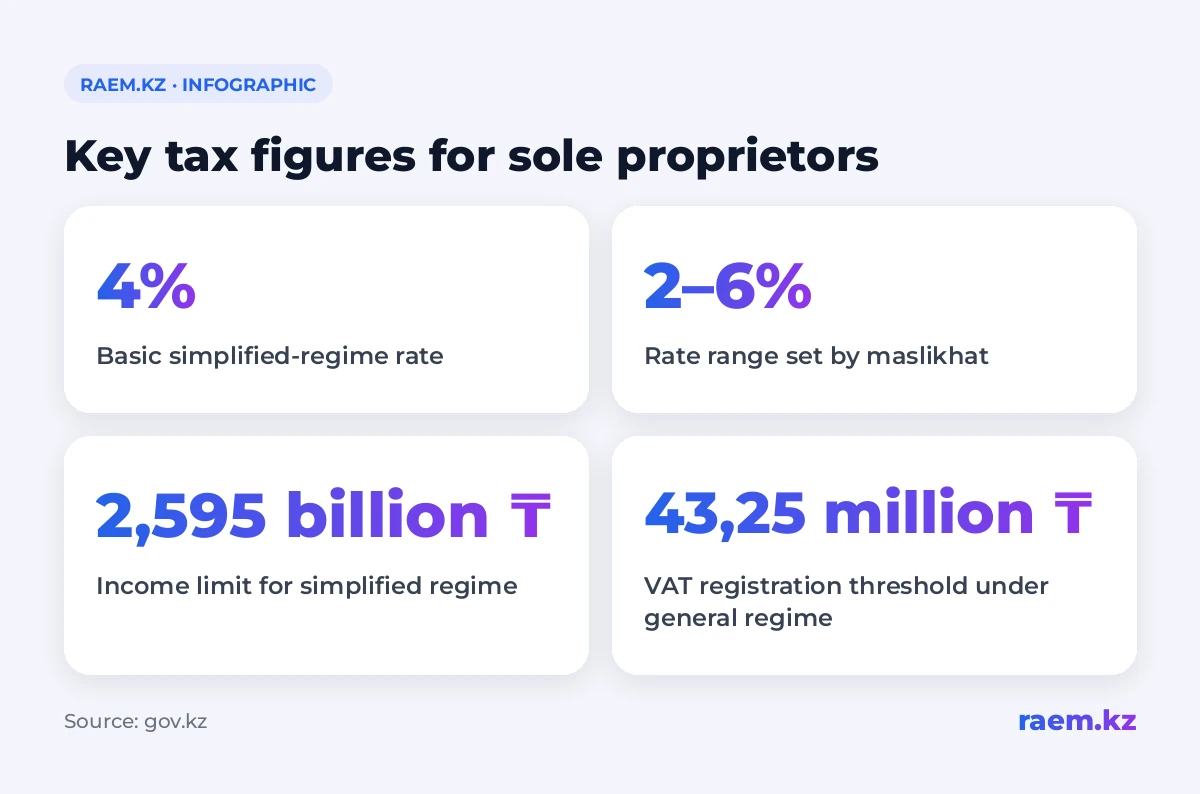
Taxes for sole traders selling on marketplaces in Kazakhstan in 2026 depend on their tax regime: the basic rate under the simplified regime is 4% of income. According to guidance from the State Revenue Committee, maslikhats can adjust it within a range of 2–6% (State Revenue Committee guidance on gov.kz). Rates and calculation rules differ under the general tax regime. Social contributions must be calculated separately.
Who can use the simplified tax regime in 2026
Under the new Tax Code, No. 214-VIII of 18 July 2025 (adilet.zan.kz), the simplified regime is available to entrepreneurs with annual income of up to 600,000 monthly calculation indices, or MCI. With the MCI set at 4,325 tenge, that amounts to 2,595 million tenge per calendar year.
But staying within the limit is not enough. The business activity must not appear on the government’s list of activities excluded from the regime. Restrictions also apply to ownership interests in other companies, including sole traders who hold a stake in a legal entity using a special tax regime.
There is no separate retail tax regime in 2026. The previous simplified and retail tax regimes have been merged into an updated simplified declaration regime.
How much tax sole traders on marketplaces in Kazakhstan pay in 2026
At the basic rate of 4%, personal income tax, or PIT, on income of 1 million tenge comes to 40,000 tenge. This is an illustrative calculation with no adjustments. Social contributions are not included in this amount.
Maslikhats can adjust the basic rate by no more than 50%, bringing it to between 2% and 6%. Check the local rate before calculating your tax.
How to calculate tax when the marketplace charges a commission
Under the simplified regime, income is counted before the marketplace deducts its commission. This approach is described in an Ösim overview on alataucitybank.kz.
For example, a buyer pays 100,000 tenge for an item. The marketplace keeps 15,000 tenge and transfers 85,000 to the seller. At a rate of 4%, the tax on this sale is 4,000 tenge: the commission does not reduce the original tax base.
Under the general tax regime, a documented commission can be treated as an expense if it meets the requirements for deductions. Expense records therefore affect the tax calculation.
How much to pay under the general tax regime
The general tax regime is known by the Russian abbreviation OUR. Sole traders pay PIT at 10% on annual taxable income up to and including 230,000 MCI.
Above that threshold, the tax has two components: 10% on the amount within the threshold and 15% on the excess. The threshold applies to taxable income. Comparing total sales revenue against it is incorrect.
When VAT and electronic invoices are required
Under the general tax regime, registration for value added tax, or VAT, becomes mandatory when turnover since the start of the year exceeds 10,000 MCI. In 2026, that is 43,250,000 tenge. The standard VAT rate is 16%.
Businesses using the simplified regime do not register for VAT. However, not being registered for VAT does not in itself remove the requirement to issue electronic invoices. Whether an invoice is required must be checked for each transaction under Article 208 of the Code and its exceptions.
When to file your declaration and pay tax
Under the simplified regime, the tax and reporting period is six months. Once it ends, two deadlines apply:
- File the declaration by the 15th day of the second month after the reporting half-year.
- Pay the tax by the 25th day of the same month.
In plain terms
If you sell on a marketplace, first check the conditions of your tax regime and the local rate. Under the simplified regime, calculate income before the marketplace’s commission and account for social contributions separately. Reconcile your sales with the marketplace’s reports before preparing your declaration.